Business Tax Accountant San Antonio AlternativeThe address decides the rate
The sale's side of the city limit decides the rate for owners in San Antonio. The city's name printed on the invoice is not the test.
Compare the rates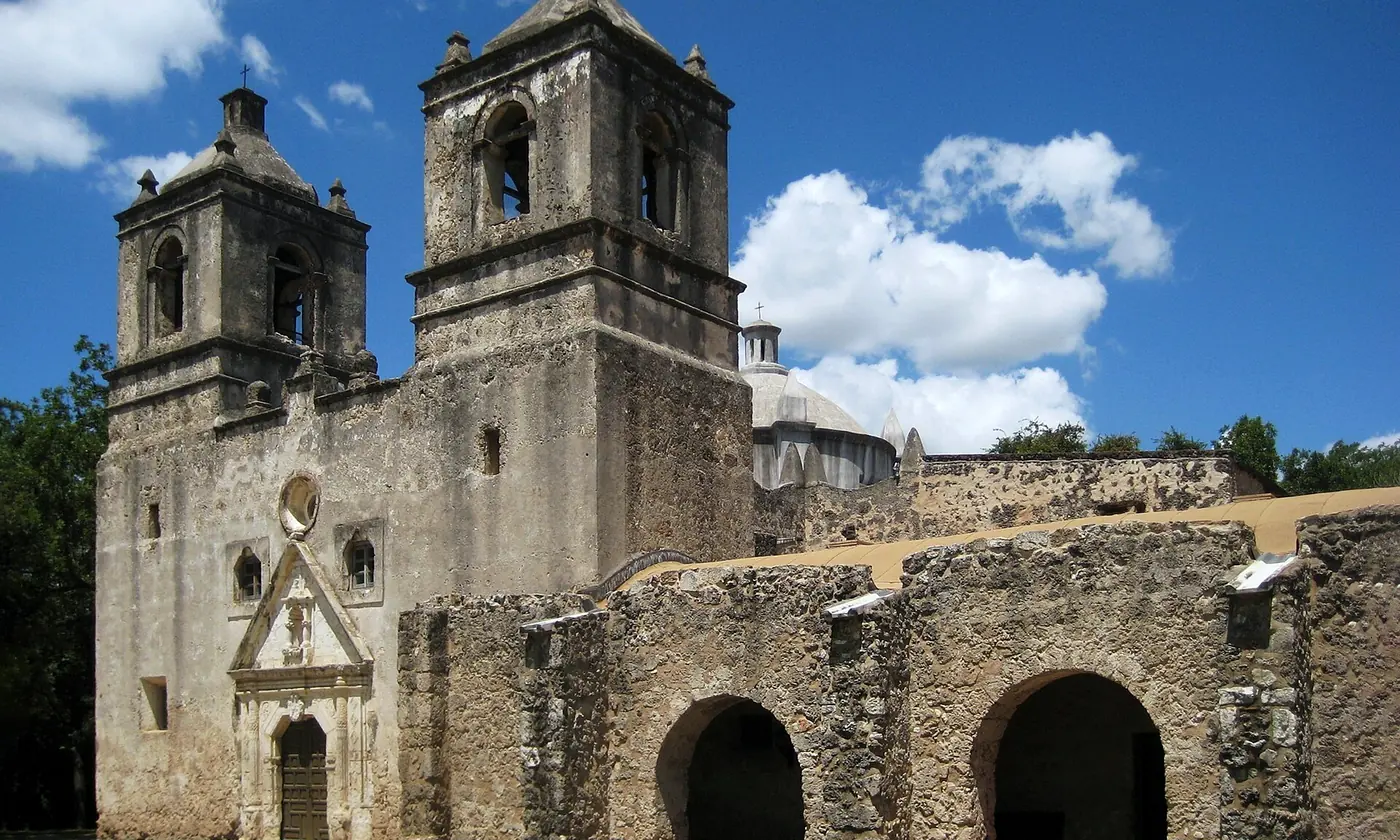
Which side of the city limit the sale was on.
Loop 1604 is the drive Texans use when they want to feel the edge of this city without stopping. Subdivisions thin, then thicken again. The sales tax can change on that same kind of stretch, and it does not announce itself with a billboard.
A sale inside the city tops out at a combined 8.25 percent. State 6.25, city 1.125, VIA 0.5, Advanced Transportation District 0.375. The city 1.125 includes the 0.125 Pre-K 4 SA slice inside the general city piece. Cross into unincorporated Bexar and the city piece falls away. An emergency services district may add a local piece instead.
Most of those districts add 1.5 percent of local tax. ESD 9-A adds 0.25 percent. Bexar County itself adds none. A job site, a delivery, or a warehouse on the county side of the limit is not taxed as if it were a counter on the river.
Why a Friday night does not settle the question.
Mission Concepcion sits inside the city, and a sale there follows the city stack. A yard twenty minutes farther out can sit past the line. The mission does not tell you the rate at that yard.
We read the address on the sale before we read the rate in someone's memory. If the books use one rate for every invoice, the monthly return will be wrong in a way that looks tidy. Tidy and wrong is the version that takes the longest to unwind.
Delivery rules and job-site rules are facts about the sale, and they belong in the close. We would rather mark an invoice unknown than force it into the city pile. Unknown is a list. Wrong is a later letter.
What we put in the close when the map is mixed.
A simple split is enough. City-limit sales in one column. ESD sales in another, named by the district when we know it. A third column for anything still unmarked. The return is prepared from the columns, not from a blended percentage that no agency published.
This is ordinary bookkeeping with a map beside it. A locator study is a different engagement, and a promise that every future address is already judged would be a different one too. When a new job site opens, the column has to be chosen again.
If your worry is a letter that says the local piece was short, bring the letter and the address list. We will say what the books show and what is still a gap. Booking the conversation creates no signed scope and no fee.
A hypothetical invoice, with the money left off.
Picture a contractor who bills one rate for every job because the software had a single tax code on the day it was set up. One job is a counter inside the city. Another is a slab past Loop 1604, in a district that publishes its own local piece. Both invoices look professional. Only one of them matches an agency.
Write the invoices into three piles before anyone debates a percentage. Which invoices used the city stack. Which ones belong to a named district. Which ones nobody has located yet. We do not invent a blended percentage to make the list shorter. A shorter pile is how that letter got written.
This picture is not a client and not a result. If it feels familiar, say so on the form without the figures. Figures belong in the books.
A job past Loop 1604 that still carries the city stack is the invoice we pull out before the return is prepared.
City limit or past it
Say whether sales stay inside the city.

You will be talking to the Steven Palmieri practice.